Bitcoin Cash · Peer to peer
Your money,
your control.
Money has gone digital, but control remains with banks, payment processors and other intermediaries. Paytaca brings it back to everyday life through Bitcoin Cash, owned, sent and received directly, without permission, borders or unnecessary fees.
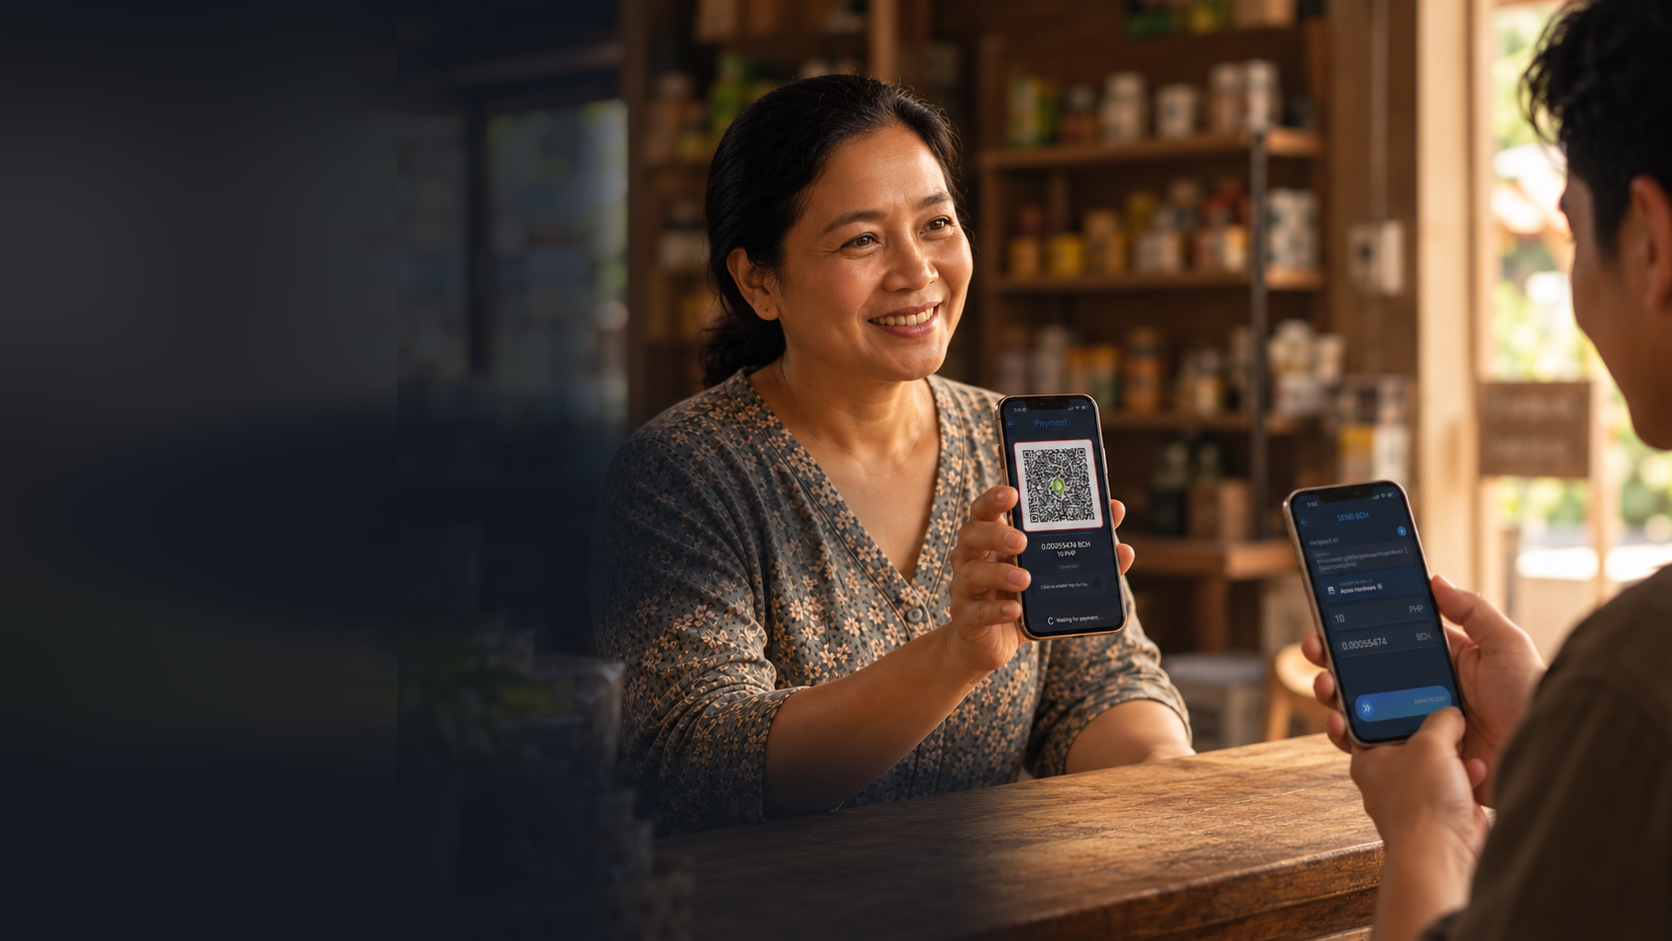
Peer-to-peer payment, no terminal in the middle · Paytaca Wallet
The problem
Someone always stands between you and your money.
Digital money doesn't move person to person. It moves through a chain of intermediaries that each have to be asked, trusted and paid.
- 01
Centralization
- 02
Trust
- 03
Inefficiency
- 04
Loopholes
1.3B
Adults with no bank account
World Bank Global Findex 2025
900M
Own a phone, but no account
World Bank Global Findex 2025
6.4%
Average cost to send $200
World Bank, Q3 2025
The inversion
Two things remove the middleman.
Not a better intermediary, no intermediary. There is nothing left to trust, because there is no one left to trust it with.
Self-custody
You hold the asset itself, not a promise about it. The keys live on your device, and no one else can freeze the funds, cap a withdrawal, or spend them without you.
- Keys on your device, not a company's server
- Nothing to bail in, and no balance sheet to fail
Peer-to-peer transfer
Payment moves straight from payer to payee and settles on a public chain. There is no processor in the middle, no counterparty to trust, and no queue to wait in.
- Final in seconds, and irreversible
- No account, no approval, no permission to ask for
Intermediated
Peer-to-peer
Cost
Intermediated
A cut on every hop: 6.4% to send money home, and fixed fees on small payments.
Peer-to-peer
Fractions of a cent per payment, at any size.
Finality
Intermediated
Days to settle; cards can reverse money already spent.
Peer-to-peer
Settled in seconds, and irreversible.
Permission
Intermediated
Granted by an institution, and revocable by one.
Peer-to-peer
None required to hold, send or receive.
Privacy
Intermediated
Balances and spending are visible to the middleman.
Peer-to-peer
No account, no personal data, nobody in the middle to watch.
Failure mode
Intermediated
Freezes, withdrawal limits, insolvency, outages.
Peer-to-peer
No single point of failure between payer and payee.
The rail
A peer-to-peer electronic cash system.
Satoshi Nakamoto · Bitcoin whitepaper, 2008
Bitcoin Cash carries that design forward. These are not features. They are the requirements from the comparison above, met on one rail.
- Settlement
- Seconds, not business days. Merchants can accept a payment with zero confirmations.
- Cost
- Fees of a fraction of a cent make small purchases economically viable.
- Tokens
- CashTokens are native, so loyalty points, tickets and stable-value assets sit on the same rail as cash.
- Programmability
- Smart contracts enable escrow, hedging and multisig without a separate chain.
- Custody
- Users hold keys directly. No intermediary sits between a payer and a payee.
- Ethos
- Peer-to-peer first, maintained in the open by the community that carried the original idea forward.
In your hand
Own your money. Spend without asking permission.
One app holds the balance, the tokens and the transactions. No account to open, no custodian holding the keys, and no one to ask before you pay.
- Send
- Pay anyone, anywhere, without asking permission.
- Receive
- A QR code and a request: no terminal, no account.
- Get BCH
- Trade cash, bank transfer or e-wallet for BCH, peer to peer.
- Spend BCH
- Pay merchants, load your phone, settle bills.

Cash in and out by trading with people
The P2P ramp matches a buyer with a seller: cash, bank transfer or e-wallet in, Bitcoin Cash out, escrowed on-chain so neither side has to trust the other. Cash-in machines cover the places where no exchange account exists.
Run the shop from the wallet
Merchant Admin controls the POS terminals from the same app. The wallet is the owner's side of the counter, which is why the next question is how a two-sided network starts at all.
The network
A payment network doesn't boot itself.
Merchants won't accept money nobody carries. Nobody carries money nobody accepts. Stated out loud, the answer is obvious: give each side a product it wants for its own sake, and let the payment rail ride along.
Supply · reason to accept
Merchant-side products wanted on their own terms: a till, a storefront, load to sell, invoicing, AI on tap. Accepting Bitcoin Cash is a by-product of running the shop better.
Demand · reason to hold
A peer-to-peer ramp, cash-in machines and rewards that pay for usage, so there is always something to spend.
Build only one side and nothing clears. Paytaca builds both.
Six products, six reasons to be in the shop
Payment is the by-product, not the pitch.
- 01Paytaca POS A till that runs the shop: inventory, sales tracking, instant settlement, several terminals into one wallet.
- 02Marketplace A local storefront paid in BCH, with rider dispatch for delivery.
- 03Payment Hub REST invoicing and payment links with webhooks, no account required.
- 04e-Load Mobile, cable and gaming load sold from the wallet, a daily reason to open the app.
- 05Merchant Map A public directory of businesses that accept BCH. A customer tool and an honest adoption scoreboard.
- 06Paytaca AI Frontier AI models run on the wallet and paid in BCH, a new product on a rail the merchant already runs.
But supply alone clears nothing
Nobody adopts a currency out of principle. Three stages, in order.
01 · Hold it
Into their hands
A peer-to-peer ramp trades fiat for BCH without a centralized exchange, and cash-in machines reach places with no bank branch.
02 · Spend it
A reason to part with it
Rewards and referrals paid in LIFT reward spending rather than holding, and the merchant network, marketplace and e-Load give a balance somewhere to go.
03 · Build on it
Holders into builders
Workshops and hackathons teach self-custody and ship on the rail; events and campaigns put the wallet in front of first-time holders.
Most crypto incentives reward holding, which produces balances that never move. Paying for spending is what makes a payment network a payment network.
50K+
Wallets
Created by a growing community
2M+
Transactions
Total number transacted on-chain
$1B+
Transaction Volume
Total value transacted on-chain
300+
Merchant Partners
Businesses accepting BCH
20+
Countries
With merchant presence
Where you go from here
Vote with your wallet. Be part of the change.
Live on iOS, Android and Chrome. Free, no account, no custodian. Change how money and commerce work, and keep the savings, the convenience and the freedom.
Verified Merchant Partners
Real businesses powered by Paytaca across the globe.
As Featured In
Coverage from leading technology and news platforms.

BitPinas
Paytaca has been extensively covered by BitPinas, the Philippines' leading blockchain and cryptocurrency news platform.
View articles
SunStar
Featured in SunStar, one of the Philippines' most respected news organizations, highlighting our impact on local commerce.
View articles
TechPatrol
Featured in TechPatrol, a leading technology blog in the Philippines, covering our innovative financial solutions and growth.
View articles
eLifeStyle Manila
Featured in eLifeStyle Manila, a premier lifestyle and tech blog, showcasing our journey in revolutionizing digital payments.
View articles